SpaceX’s reported plans to raise as much as $40 billion to finance purchases of Nvidia (NASDAQ: NVDA) chips are highlighting a growing concern around the way capital is flowing through the artificial intelligence industry: chip suppliers, customers and financiers are becoming increasingly interconnected.
The Elon Musk-led aerospace and AI company is reportedly seeking about $10 billion in bank loans and another $30 billion in investment-grade debt. If completed, the financing would rank among the largest debt raises associated with the AI infrastructure buildout.
A separate Wall Street consortium is also assembling about $60 billion in financing for AI chips, adding to a broader shift toward debt-funded expansion across the sector.
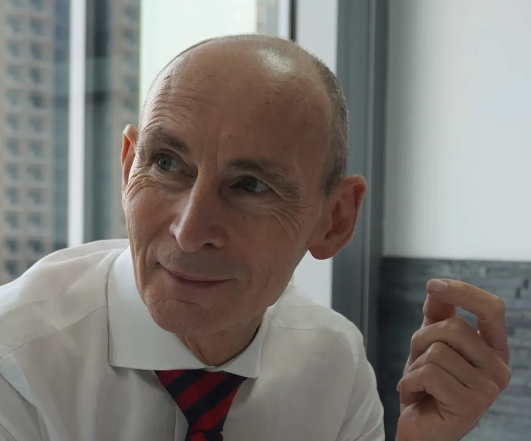
Nigel Green, CEO of deVere Group, said the SpaceX financing illustrates what he described as a circular flow of capital. Nvidia owns a significant stake in SpaceX, while SpaceX has committed to building its AI systems around Nvidia chips.
“Follow the money here and it comes straight back to where it started,” Green said.
Nvidia’s Growing Role in AI Financing
Regulatory filings show Nvidia held just under 123 million SpaceX shares, valued at nearly $21 billion at the end of June, according to the information provided.
Nvidia has also committed more than $100 billion to AI companies since 2024 and is working with Wall Street firms on financing arrangements that could provide more than $500 billion to its customers. Some of those structures reportedly involve guarantees tied to the value of Nvidia chips.
The financing model has raised questions about how much of the industry’s reported growth reflects independent end-user demand and how much comes from capital circulating between suppliers and their customers.
“When a supplier guarantees the loans its customers use to buy its products, and those loans are secured against the same products, everything rests on chip values holding up,” Green said.
The issue becomes more significant if new generations of AI hardware reduce the useful economic life of existing chips faster than expected. In that scenario, chip values, collateral and equity holdings could decline simultaneously.
Debt Adds Pressure to AI Infrastructure
SpaceX’s reported financing plans come against a backdrop of heavy spending across the technology sector. Big Tech companies are expected to invest about $700 billion in capital projects this year, with roughly three-quarters directed toward AI infrastructure, according to the information provided.
At the same time, much of the hardware is being depreciated over five to six years. Critics argue that the economic life of some AI equipment could be closer to two or three years, potentially leaving companies with costs that are recognized too slowly.
One estimate cited in the material puts the resulting understatement of costs at about $176 billion between 2026 and 2028.
“Stretching depreciation flatters today’s profits by pushing the costs into future years,” Green said.
The combination of financing structures and depreciation assumptions could therefore affect how investors assess the profitability and sustainability of AI infrastructure spending.
AI Buildout Moves Toward Credit
The funding environment is already shifting from primarily cash-funded investment toward debt. Analysts cited in the material expect about $300 billion of investment-grade bonds to finance AI data centers this year alone.
That transition could broaden the financial consequences of an AI slowdown. Equity investors can absorb volatility through changes in share prices, but debt requires scheduled repayment regardless of whether projected revenues materialize.
Green said increasing reliance on credit means risks could extend beyond technology companies and into bond funds, pension portfolios and other institutional investments.
The central question is whether AI companies can generate enough long-term revenue and productivity gains to support the scale of capital being committed today.
“Circular money makes a boom look stronger on the way up and fall harder on the way down,” Green said. “If they don’t, the losses won’t stay inside Silicon Valley and they’ll be shared by investors far beyond the companies at the centre of the loop.”